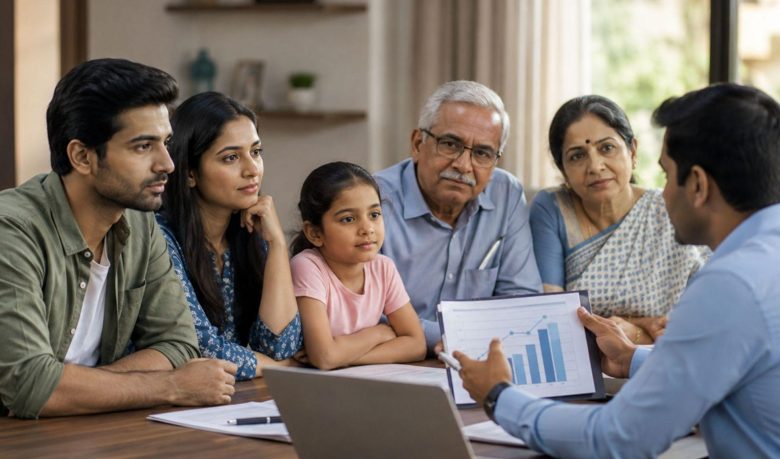
Health insurance premiums can differ even when two people are looking at similar cover. This happens because insurers consider several details before deciding the premium. Age, the amount of cover selected and the city of residence can all affect expected healthcare costs and claim risk.
Each factor changes the insurer’s assessment differently. Understanding these reasons makes it easier to see why one person may receive a different premium quote from another overall.
Age Can Increase Expected Healthcare Needs
Age affects premiums because healthcare needs often change as people grow older. Older individuals may require more frequent medical consultations, tests or treatment than younger adults. Insurers take this expected difference in healthcare use into account while assessing risk.
As a result, premiums may rise with age under many policies. If you compare health insurance plans, it helps to check how age bands are treated rather than assuming every insurer follows the same pricing pattern.
Age Can Also Affect Expected Claim Risk
Age can also influence the likelihood of certain medical conditions developing over time. Insurers therefore consider the age of each person covered when estimating possible future claims. In a family policy, the age profile of members may affect the overall premium, depending on the plan structure.
This is why adding an older member can change the quote. The exact impact varies by insurer, product design, medical history and applicable underwriting rules for the selected policy.
A Higher Sum Insured Increases Financial Exposure
The sum insured affects premiums because it decides how much financial cover is available for eligible claims. A higher sum insured means the insurer may have to pay a larger amount if a covered hospitalisation or treatment occurs.
Because the potential financial responsibility is greater, the premium can also increase. A lower sum insured may reduce the premium, but buyers should make sure the chosen amount remains suitable for expected healthcare needs and family circumstances.
Larger Cover Can Change the Premium Calculation
A larger sum insured can be useful where medical costs are high or several family members share the same policy. However, increasing cover changes the insurer’s exposure, so the premium is recalculated.
Buyers should therefore look at the relationship between cover amount and premium rather than considering either one alone. The right balance depends on personal needs, family size, preferred hospitals and the type of treatment expenses the policy is expected to support over time.
City Can Affect Local Treatment Costs
City of residence can influence premiums because medical expenses are not the same everywhere. Hospital room charges, consultation fees, diagnostics and specialist treatment can vary between metro cities and smaller locations.
Insurers may use the residential PIN code or city to understand the local healthcare cost environment. Where expected treatment costs are higher, the premium may be different. However, city-based pricing depends on the insurer and the specific health insurance product being offered overall.
See also: The Boston Business Upgrade Nobody Talks About Enough
Access to Healthcare Can Differ by Location
Large cities may also have greater access to speciality hospitals, advanced treatment facilities and a wider range of private healthcare services. These factors can influence the average cost and type of claims made in that location.
Smaller cities may show a different treatment and claim pattern. Insurers may consider such regional differences while pricing a policy. This does not mean every metro resident will pay more, because location is assessed with other personal and policy factors.
Age, Cover and City Can Work Together
Age, sum insured and city often work together rather than affecting the premium separately. For example, an older applicant choosing a larger cover amount in a high-cost city may present a different risk profile from a younger applicant selecting lower cover elsewhere.
The premium reflects the complete set of information provided during the proposal process. This is why changing one detail can produce a different quote, even when the basic policy type remains unchanged.
Final Thoughts
Health insurance premiums vary because age, sum insured and city influence the insurer’s view of expected healthcare needs and financial risk. Age can affect likely medical requirements, a higher sum insured increases the amount of cover available, and city can reflect local treatment costs.
These factors are considered along with other personal and policy details. Entering accurate information and comparing similar cover options can help buyers clearly understand why premium quotes differ across different plans.